Key Takeaways
- An interactive teller machine does everything an ATM does and adds a live teller by two-way video, so customers and members can finish teller-line transactions at the machine.
- ITMs handle check cashing, denomination selection, loan payments, and transfers across all accounts when the machine is integrated with the institution’s core.
- Core integration decides which transactions an ITM can complete on its own, and it is usually the longest part of a deployment.
- Up to 90% of teller transactions can shift to self-service.
An interactive teller machine, or ITM, is a self-service machine that does everything an ATM does and connects the customer or member to a live teller by two-way video when a transaction needs one. For banks and credit unions, it has become the most practical way to keep full-service transactions available at hours and in locations where staffing a teller line no longer makes sense.
The gap it fills is familiar to anyone who runs branches. A teller line is expensive to staff and hard to extend past branch hours, and much of its day goes to transactions that do not need a person in the room. An ATM absorbs withdrawals and simple deposits, but anything beyond that sends the customer or member back inside, to a line that may be closed, short-staffed, or several miles away. The ITM exists to close that distance.
What an Interactive Teller Machine Is
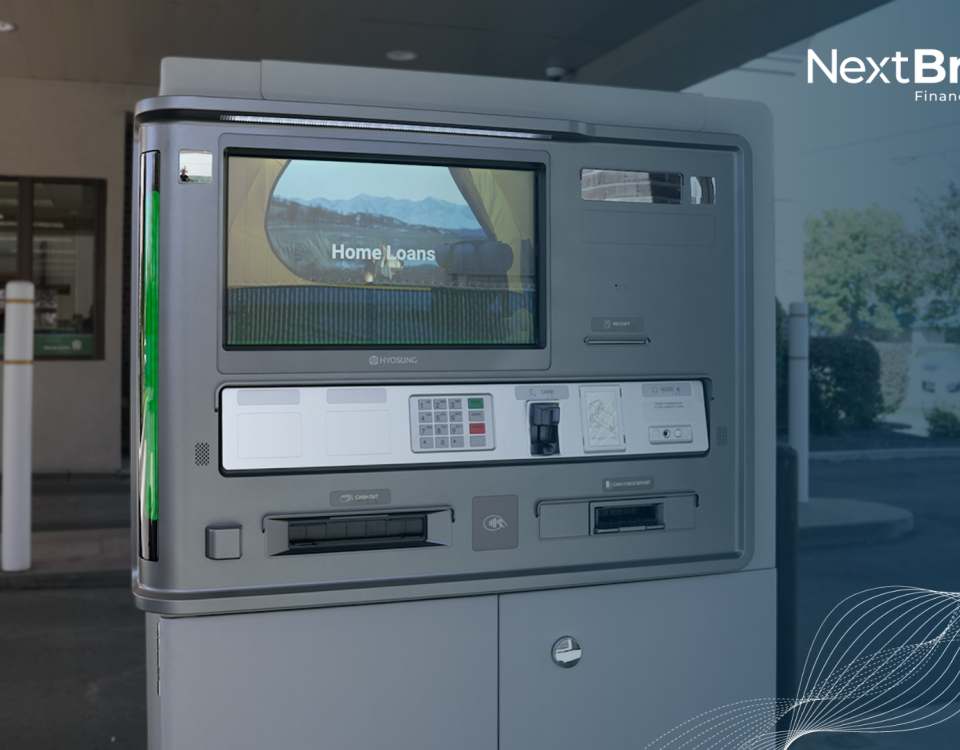
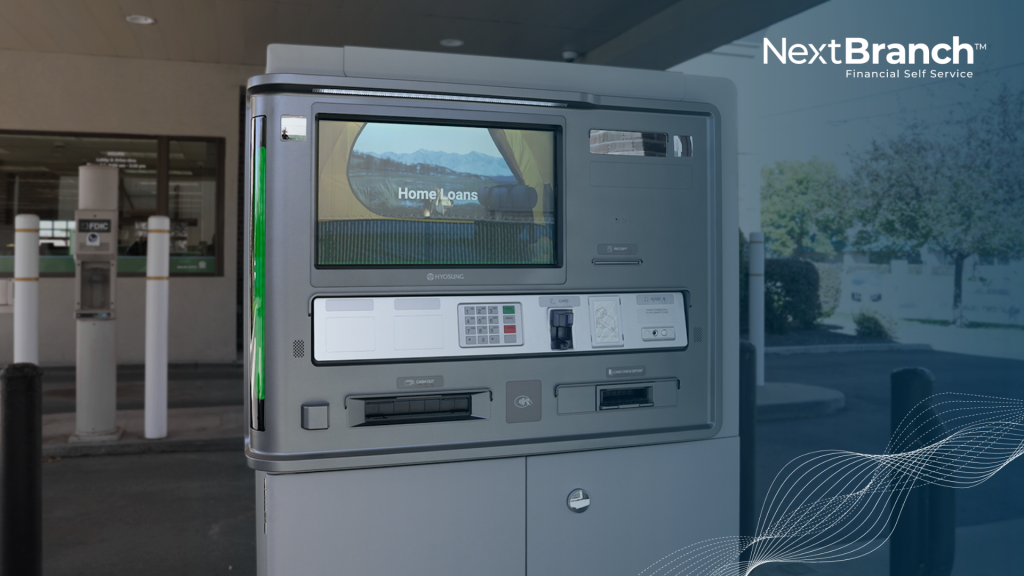
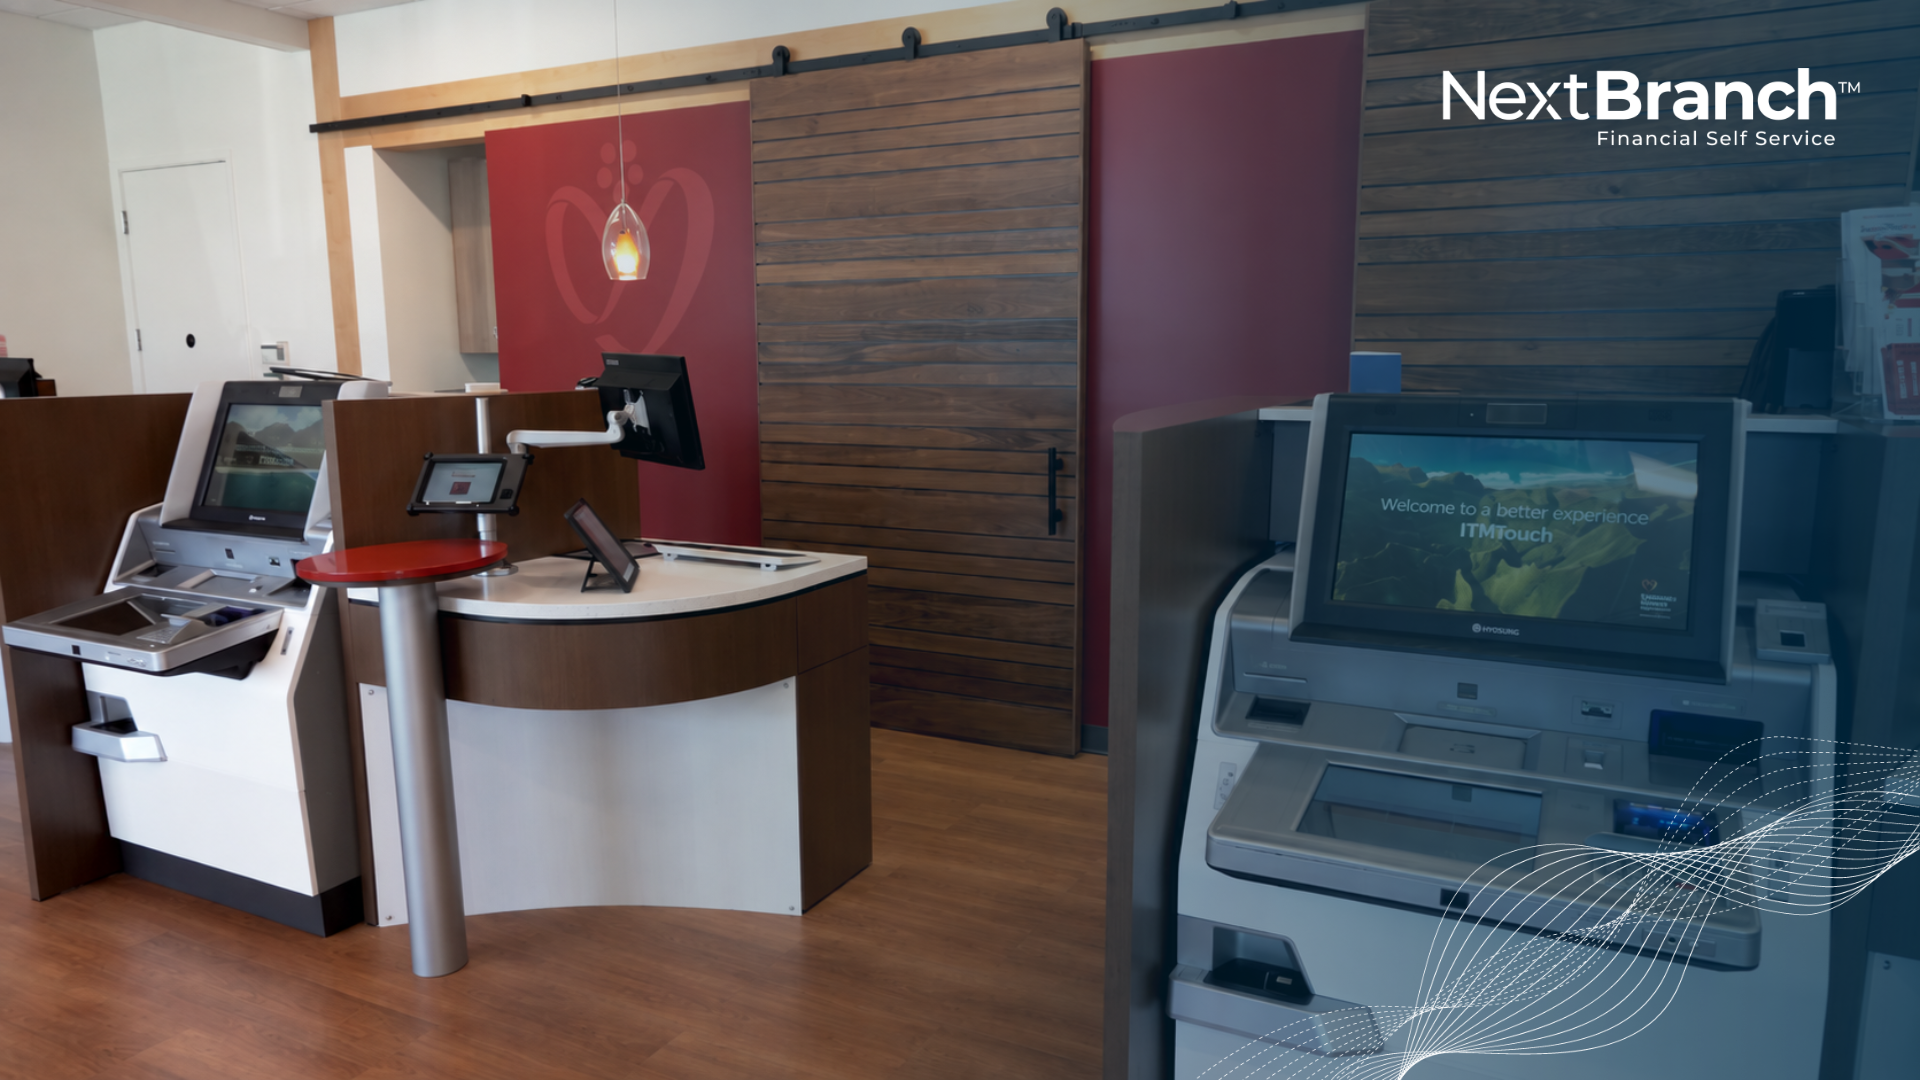
Physically, an ITM resembles a large ATM. It has the same screen, card reader, cash dispenser, deposit module, and receipt printer, along with a camera, microphone, and speaker for the video session. The difference is in how it works, because an ITM runs in two modes.
In self-service mode it behaves like an ATM, and the customer or member completes routine transactions alone. In assisted mode, a tap on the screen opens a video session with a remote teller, who can verify the person’s identity, see the relevant accounts, and approve transactions that an ATM cannot handle, such as cashing a check or raising a withdrawal limit. The machine then completes the transaction on the spot.
Remote tellers typically work from a central location rather than from the branch where the machine sits. That arrangement is what makes the model efficient, since one team of video tellers can support machines across an entire network, including locations that never had a teller line at all.
What an ITM Can Do That an ATM Cannot
| Capability | ATM | ITM |
| Cash withdrawals and deposits | Yes | Yes |
| Transfers | Between linked accounts | Across all accounts, through core integration |
| Check cashing | No | Yes, approved by a remote teller |
| Denomination selection | Some models | Yes |
| Loan payments | Not in most deployments | Yes |
| Live teller assistance | No | Yes, by two-way video |
| Withdrawal limits | Fixed | Adjustable by the remote teller |
| Hours | 24/7 self-service | 24/7 self-service, with video teller hours set by the institution |
The practical difference is where a transaction ends. At an ATM, anything unusual ends the session and sends the customer or member inside. At an ITM, the same moment becomes a conversation with a teller, and the transaction finishes at the machine. For help choosing a machine for each location, see ITM vs ATM: Which One Does Your Branch Need?
What Customers and Members Can Do at an ITM
The feature set that matters most is the one that replaces a trip to the teller line: a live video teller for anything that needs a person, check cashing, denomination selection so the machine dispenses the bills the customer or member actually wants, loan payments, and access to all of their accounts through integration with the institution’s core system, rather than only the account tied to the card.
The objection that comes up most is about people. Customers and members sometimes worry that the institution is replacing its staff with machines. The answer is in how the machine works: every video session is a conversation with one of the institution's own employees, and the staff who once worked the teller line spend more of their time on lending, advice, and growing relationships.
How the Remote Teller Connection Works
A typical assisted transaction runs in four steps. The customer or member starts a transaction at the machine and requests help, and a video session opens with the next available remote teller. The teller confirms identity and reviews the account, then approves the transaction, whether that means authorizing a check, adjusting a limit, or walking the person through a payment. Finally, the machine completes the transaction, dispensing cash or printing a receipt, while the teller stays on the call until it finishes.
Because the remote teller is centralized, the institution decides how many video tellers to staff and during which hours, independent of branch opening times. Self-service remains available around the clock, and video assistance extends as far into the evening or weekend as the staffing model supports.
Why Core Integration Decides What an ITM Can Do
An ITM is only as capable as its connection to the institution’s core system. Core integration is what allows the machine to show all of a customer’s or member’s accounts, post loan payments, and move money between accounts without manual work behind the scenes. It also tends to be the longest part of a deployment, because it involves three parties: the institution’s core provider, the machine manufacturer, and whoever manages the machines.
Integration can also be phased when the timeline or the core roadmap requires it. Some institutions replace their ATM fleet with ITMs and turn on video teller first, then connect the core at a later stage.
Where ITMs Fit in a Branch
Most institutions deploy ITMs in one of three places. In the lobby, they take over a large share of the transactions that once filled the teller line, and up to 90% of teller transactions can shift to self-service. In the drive-up lane, they extend full-service transactions to customers and members who never leave the car. In small-footprint and extended-hour locations, they make a branch viable where a full teller line never would be.
The staffing effect is as significant as the space effect. Because the machine handles the routine work, a branch needs fewer people on the teller line, which matters for institutions that struggle to hire and keep tellers.
What to Settle Before Deploying ITMs
Four decisions shape how well an ITM program performs, and each is easier to make before the first machine arrives than after.
- Which transactions go where. Decide which move to self-service, which go to the video teller, and which still belong with a person in the branch.
- Video teller staffing and hours. Decide who staffs the remote teller function, from where, and during which hours.
- The core integration path. Confirm what your core provider supports, how long testing takes, and whether a phased rollout makes sense.
- Ownership of the running fleet. Decide who handles service, software, compliance upgrades, and vendor management once the machines are live, since an ITM carries every obligation an ATM does plus the video platform.
Cost depends on configuration, integration model, and staffing, and deserves its own analysis once those four decisions are made. For a view of the deployment process itself, see what ATM and ITM implementation looks like.
NextBranch provides fully outsourced ATM, ITM, and teller cash recycler management for community banks and credit unions, covering equipment, expert managed services, compliance, and vendor management under one monthly fee, and the subscription maintains the latest technology across the fleet. The company is a subsidiary of Grant Victor, Hyosung’s largest U.S. reseller partner, and its managed fleet ran at 99% uptime in 2025. Schedule a consultation to see how ITMs would fit your branches.
Frequently Asked Questions
What is an ITM?
An interactive teller machine is a self-service machine that does everything an ATM does and connects the customer or member to a live remote teller by two-way video. The remote teller can verify identity, see accounts, and approve transactions such as check cashing.
What is the difference between an ITM and an ATM?
An ATM handles withdrawals, deposits, and basic transfers on its own. An ITM adds a live video teller, check cashing, denomination selection, loan payments, and access to all accounts through core integration, so transactions that would end at an ATM can finish at the machine.
Do ITMs replace tellers?
No. Every assisted transaction is handled by a remote teller who is an employee of the institution. What changes is the work, since staff who spent their day on routine transactions shift toward relationship building, lending, and advice.
Does an ITM need to integrate with the core?
An ITM can run video teller sessions before core integration, but integration is what allows it to show all accounts, post loan payments, and complete transactions without manual work. Many institutions phase the rollout, turning on video teller first and integrating the core later.